
What Is COI Management Outsourcing?
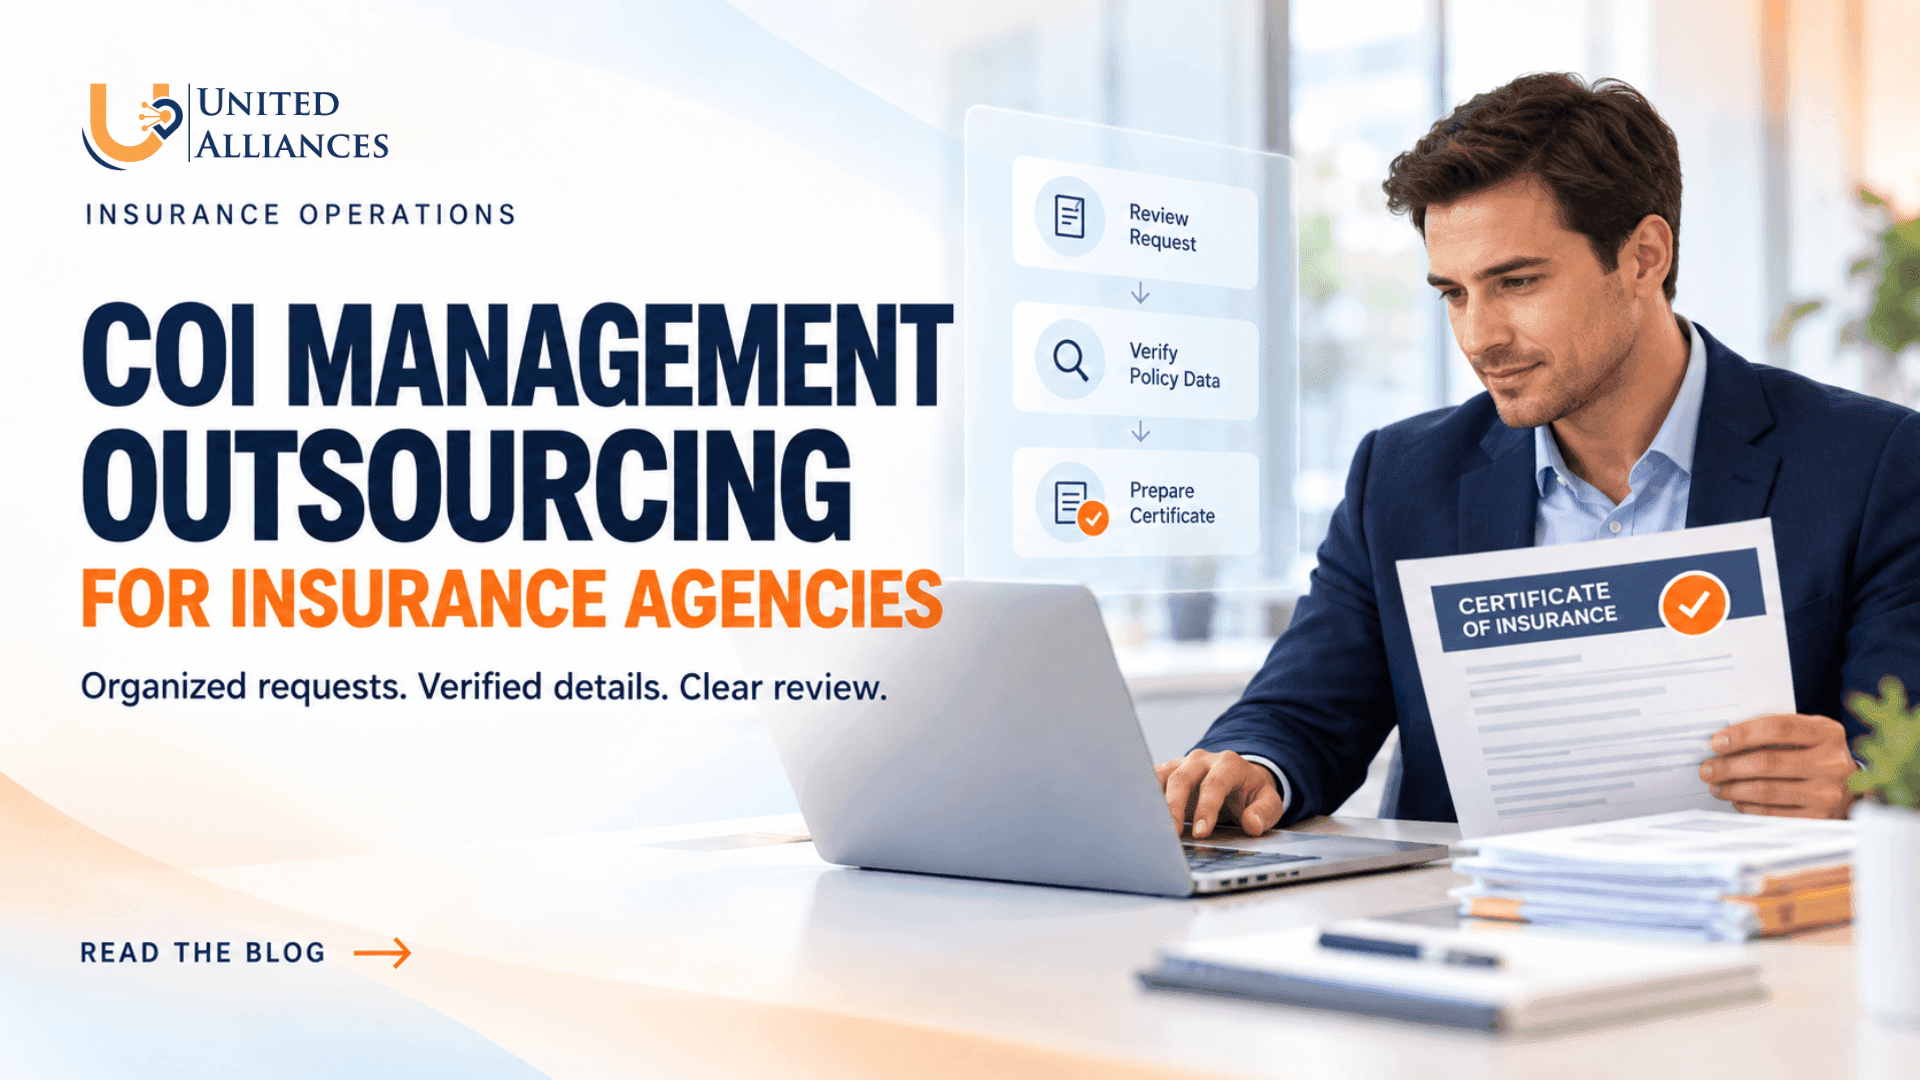
COI management outsourcing means assigning defined certificate of insurance tasks to an external support specialist or team. Typical tasks include receiving and organizing requests, checking policy data against an approved source, preparing standard certificates, maintaining certificate holder records, routing exceptions, sending approved documents, and logging completion. The agency decides what can be issued under its authority and retains coverage advice, policy changes, and approvals that require licensed judgment.
A certificate generally provides evidence of insurance. It does not create coverage or rewrite a policy. New York's Department of Financial Services explains that certificates should not amend, expand, or otherwise alter policy terms. State-specific rules matter too; the Texas Department of Insurance's certificate guidance addresses approved forms and how certain additional insured, waiver, and notice requests may be described for Texas risks. Agencies should apply the rules relevant to the risk, form, carrier, and jurisdiction rather than assume one certificate procedure fits every account.
Which Requests Can Go Through a Standard COI Queue?
A standard request usually asks for evidence of coverage already in force, using an approved form and information that the agency can verify. It may identify a new certificate holder and delivery address without asking to change limits or policy terms. Even here, the support team should confirm the right insured, policies, dates, and holder details before release under the agency's procedure.
Other requests need review before a document goes out. Consider three practical lanes:
| Request Lane | Typical Request | Next Owner |
|---|---|---|
| Standard | Evidence of current coverage for a holder, with no special wording beyond the approved form | Trained certificate processor under the agency's written authority and review rules |
| Verify | Holder asks for additional insured status, waiver of subrogation, primary and noncontributory wording, or a particular notice provision | Account manager checks policy and endorsements; carrier or producer handles unresolved terms |
| Change | Requested limits, insured name, coverage, endorsements, or dates do not match the policy record | Licensed agency staff determines the next step and seeks carrier action where needed |
These lanes are a routing method, not a legal classification. A blanket endorsement, for example, can require careful review of its conditions and how the certificate may describe it. Texas Department of Insurance guidance gives specific examples in which a certificate cannot simply name a holder as an additional insured or as the beneficiary of a waiver when only a blanket endorsement is present. The correct treatment depends on the policy language and applicable law. A processor should flag the request instead of improvising certificate wording.
How Should the COI Workflow Run From Request to Delivery?
The goal is a queue where anyone covering the account can see what is waiting, why it is waiting, and who must act next. An emailed PDF is only the final artifact; the work starts before the form is prepared.
Capture the Request in One Place
Record the requesting party, insured, policy or account, certificate holder's exact name and address, delivery contact, requested deadline, job or contract reference if relevant, and the wording or endorsements requested. Attach the original request. Ask for missing information through an approved channel. A holder's contract can be useful context for the agency reviewer, but it is not a source from which a processor may invent policy coverage.
If a request arrives from a third party, verify which insured account it relates to and whether the insured has authorized the agency's release process. Agencies should set their own identity and privacy checks for the information being sent. A reused holder entry in the AMS may save typing, but it does not prove the present request is the same as last year's.
Check the Policy and Form Before Preparing the Certificate
Use the current policy and endorsement record as the source for carrier, policy number, coverage, limits, effective and expiration dates, and any represented status. Confirm that the selected form is approved for the relevant workflow. A renewed account may have new policy numbers or terms even when the holder name has not changed.
The Texas Department of Insurance's published certificate form example illustrates the ordinary disclaimer that a certificate is informational and does not change policy coverage. It also notes that additional insured status must come from policy provisions or an endorsement. The form itself cannot be used as a shortcut around a missing policy term.
Route Exceptions With a Precise Question
“Please review COI” is not enough for a busy account manager. Identify the exact conflict: the contract asks for a higher limit than the policy shows; the holder wants a notice provision not shown in the policy; the requested additional insured wording differs from the endorsement; or the policy has expired in the AMS while renewal documents are still pending. Attach the relevant source and set the item to a review status.
The agency reviewer then decides whether the policy already supports the request, whether to seek a carrier endorsement, or whether to explain a limitation to the client. The support specialist should not promise that an endorsement will be issued or that a certificate itself satisfies a third party's contract.
Release, Record, and Close
Once the certificate has passed the agency's review rule, send it through the approved channel to the intended recipient. Save the issued copy and delivery record with the insured's account, including the holder, date, request reference, reviewer if required, and any related endorsement. If a requested policy change remains pending, keep that work open separately; do not close it merely because a certificate was sent.
That last step is easy to miss in a high-volume queue. A certificate holder may reply with a rejection or new requirement after the first delivery. The team needs an owner and status for that response, rather than starting a disconnected email chain.
What Makes Construction and Multi-Location Accounts Harder?
One insured may need certificates for dozens of general contractors, project owners, landlords, and locations. Each request can carry a different holder name, contract reference, delivery portal, and deadline. The volume is repetitive, but the wording is not necessarily interchangeable.
Take a hypothetical subcontractor serving three jobsites. Two holders ask only for evidence of existing general liability and workers' compensation coverage. The third asks to be named as an additional insured with a waiver of subrogation and a specific cancellation notice. The first two may follow a standard agency procedure after verification. The third belongs in a review lane until the account manager checks the actual endorsements and applicable form rules. Copying a prior certificate could reproduce an error or suggest a right the policy does not grant.
For recurring holders, store approved names, addresses, portal instructions, and past documents in the AMS or another controlled system. Recheck the policy and request each time. A reusable holder record should reduce data entry, not bypass current-policy verification.
Which Controls and Measures Are Worth Keeping?
The agency should write a short procedure that names the source of truth, permitted form, approval rule, prohibited wording, escalation owner, delivery method, and completion evidence. Give a support person individual system access limited to assigned work. Do not share a producer's credentials or let a certificate queue become a place for unapproved policy changes.
Measure the queue in a way that explains delay and quality. Useful fields include request receipt time, completeness of intake, standard or exception lane, current owner, reason for a pause, delivery time, and any holder rejection or corrected certificate. A single average turnaround figure can hide requests waiting on the client, carrier, or internal approval. Review a sample of completed standard requests and every material exception until the procedure is reliable.
When evaluating a provider, ask to see a sample request log and an anonymized exception handoff. Can the team show which policy record it checked? Does it distinguish “prepared,” “awaiting agency review,” “sent,” and “rejected by holder”? Who handles an urgent request when the regular assistant is absent? These answers reveal more than a promise to process a set number of certificates per day.
How United Alliances Supports Certificate Work
United Alliances' Commercial Lines Virtual Assistant service lists COI issuance, ACORD form preparation, and document updates among its support tasks. Its insurance back-office outsourcing service describes standard certificate work in an agency's AMS and states that licensed advice and binding authority stay with the agency.
An agency considering this support can begin with its real certificate queue: which requests are standard, which wording sends an item to review, what the current policy source is, who approves a release, and how a rejected certificate returns to the team. That gives United Alliances and the agency a concrete scope to agree on before more holders or accounts are assigned.
A Reliable COI Queue Has an Exception Path
COI management outsourcing works best when the routine steps are easy to delegate and the unusual ones are easy to stop. A complete request has a verified policy source, the right form, an authorized review when needed, the delivered certificate, and a retrievable record. If a holder asks for coverage the policy does not show, the queue should make that difference visible to the agency decision-maker before anyone sends a document.