
Which Policy Lifecycle Stages Can Share One Support Model?
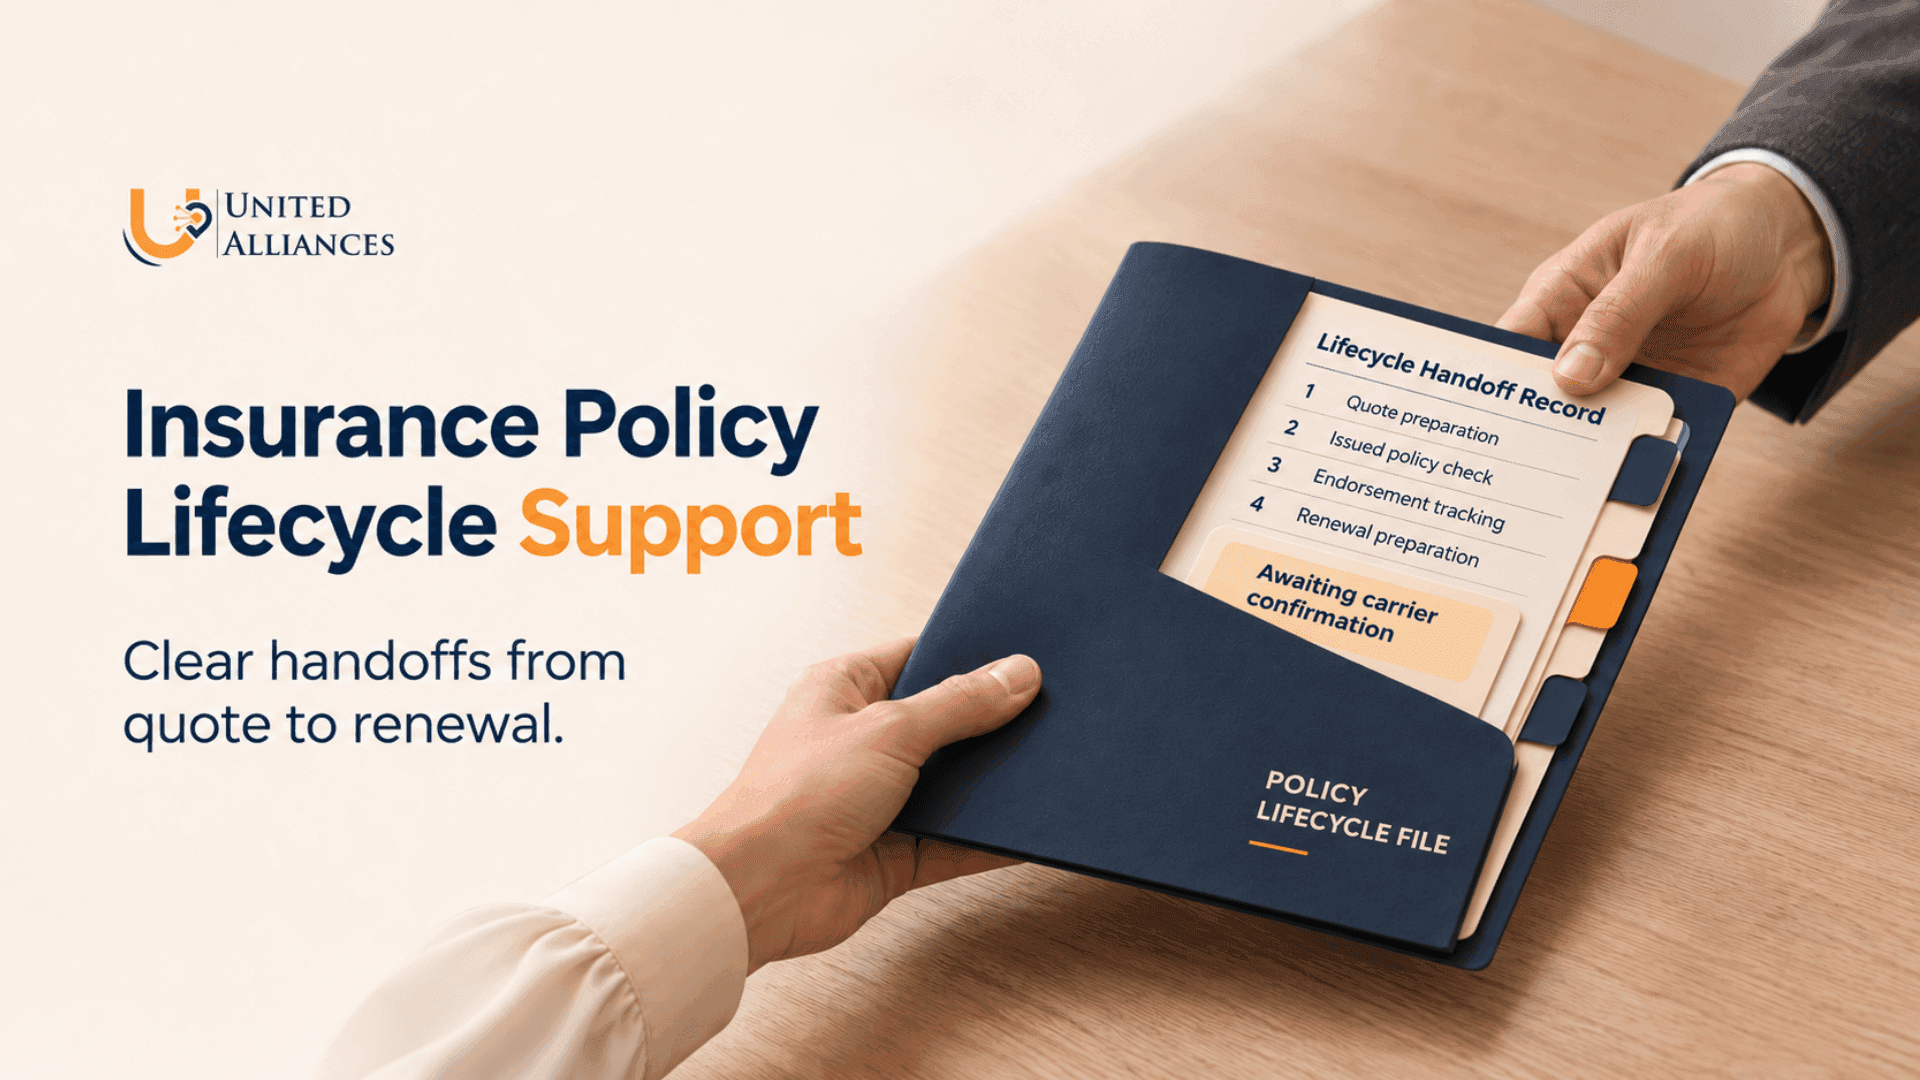
The stages connect through the policy and account record. A support provider should know what evidence closes one stage and what information the next stage needs. The division below is a starting design for an agency to adapt to its lines of business, carriers, systems, and state requirements.
| Stage | Support team can prepare or track | Agency decision or acceptance point |
|---|---|---|
| Quote and submission | Gather approved information, enter applications or portal data, attach documents, track missing items and carrier questions | Coverage design, markets, representations to the carrier, quote evaluation and client recommendation |
| Bind request and issuance | Assemble approved bind-ready material, track carrier response, index binder or policy documents, compare issued records with approved terms | Authority to bind, effective date, client confirmation and resolution of material differences |
| In-force servicing | Log client requests, prepare routine change paperwork, follow up with the carrier, reconcile issued endorsements and AMS entries | Coverage effect, unusual wording, exceptions, disputed effective dates and client advice |
| Renewal preparation | Pull expirations, gather updated exposure data, track open changes, organize current and proposed documents, flag differences | Renewal strategy, remarketing, coverage comparison, recommendation and approval |
| Record and exception management | Maintain task status, source documents, next owner, deadlines and evidence of closure throughout | Agency supervision, priority decisions, unresolved exceptions and final sign-off rules |
A single provider can support all of these stages without one individual performing every step. Some agencies need a dedicated assistant with a supervisor and backup; others need several specialists under one documented handoff. The buyer should ask who owns the account record when work moves between people.
What Must Carry Forward From Quote to Issued Policy?
The quote file contains exposure facts, assumptions, proposed terms, carrier responses, and client choices. At the transition to binding, the agency should identify the approved version and the person authorized to act. The support team can assemble that version and record the carrier's response, but a quote, a bind request, a binder, and an issued policy are distinct records. A task status should say which one exists.
After issuance, compare the carrier document to the approved terms. Check names, locations or vehicles, limits, deductibles, forms, effective dates, premium, and any subjectivities relevant to the account. The agency decides how to address a material discrepancy. The support team can log it, obtain corrections, and retain the final document where the servicing and renewal teams will find it.
This is the first test of a lifecycle model: can the provider show the approved decision, the carrier's actual response, and the final policy in the agency's system? A green “new business complete” status without those links gives the next person little to work from.
How Do Midterm Changes Reach the Next Renewal?
An endorsement request should create a traceable chain: client instruction, agency review where needed, carrier submission, carrier response, issued document, AMS update, and client communication. The NAIC explains that an endorsement changes an existing policy contract. That is why a portal entry should not be treated as the same event as an issued change.
Consider a hypothetical commercial account that adds a location midterm. The assistant gathers the address and operations details and logs the request. The account manager evaluates coverage implications and approves the carrier submission. The assistant records that the carrier has received the request, then follows up until the issued endorsement or a clear carrier decision is available. The final location information goes into the account record and the next renewal file. If the carrier has not issued the change, the renewal team sees an open exception instead of assuming the new location is already part of the policy.
This carry-forward rule also applies to vehicle changes, insured names, payroll or revenue updates, mortgagees, and other exposure facts, according to the policy type. The agency should decide which fields belong in the active policy record and which open items must appear on the renewal checklist. A private provider spreadsheet can help manage work, but it should not become the only place where the agency's history exists.
What Does a Usable Lifecycle Record Look Like?
The agency management system (AMS), supported by its approved document store, should make the next action understandable without a long email search. Each task should identify the account and policy, request type, source instruction, date received, requested effective date or deadline, current state, next owner, carrier reference, relevant document, and agency approval when one is required.
Use statuses that describe reality: awaiting information, prepared, submitted, awaiting carrier, awaiting agency review, issued or confirmed, and reconciled. A completed task should have a completion rule. For a routine document request, that may be delivery and an activity log. For an endorsement, it may require the carrier document, comparison to the approved request, AMS update, and agency review of any difference. “Done” means something different at each stage unless the agency defines it.
Run a short exception review across the lifecycle rather than separate meetings for quoting, servicing, and renewals that cannot see one another's open work. Look for requests nearing a client or carrier deadline, changes with no carrier confirmation, issued documents awaiting reconciliation, and renewals built on incomplete account data. The point is to expose decisions the agency needs to make, not to count every click performed by a remote team.
Where Must the Agency Keep Authority and Access Control?
Operational continuity does not authorize an assistant to advise the client or bind a risk. The NAIC's producer-licensing overview describes selling, soliciting, and negotiating insurance as licensed producer activities governed by state rules. The agency should define permitted communication, carrier portal actions, approval steps, and supervision for each jurisdiction and line of business. A specialist may prepare a comparison; the appropriately authorized agency person decides what to recommend.
Access should follow the task. Use named accounts with permissions for the assigned work, confirm the AMS and carrier's user rules, and remove access when assignments change. NIST's small-business MFA guidance recommends enabling multifactor authentication where available, limiting access to those who need it, and removing access when that need ends. Ask the provider to demonstrate how a backup person gains authorized access without borrowing another user's credentials.
The provider's security documentation matters, but the agency also needs to see a real workflow: where client files are stored, who can download them, how exceptions are escalated, and what happens to data at the end of the engagement. These choices should be explicit in the working procedure and service agreement.
How Should an Agency Test a Provider Offering Quoting, Endorsements and Renewals Together?
Give each candidate one sanitized account that crosses stages. Ask it to show a quote prepared from source information, an approved bind request, the issued policy check, a later change still awaiting the carrier, and a renewal report. The exercise reveals whether the provider keeps one usable history or treats each stage as a fresh ticket with missing context.
Ask who performs each step, who supervises the team, who covers an absence, and what the agency sees in its own AMS. Require a demonstration of one routine item and one exception. The exception is the more useful test: can the team stop at a coverage question, name the reviewer, preserve the deadline, and resume after a decision without losing the source record?
Start with connected work that the agency can supervise closely, such as submission preparation through issued policy checking, or endorsement administration feeding a renewal queue. Review samples of completed work and every material exception. Track items returned for correction, time spent awaiting carrier versus agency action, and issued documents not yet reconciled. Expand the scope when those handoffs work in practice.
How Does United Alliances Fit This Model?
United Alliances' insurance back-office outsourcing service describes support across new business and submissions, policy servicing and endorsements, renewal preparation, carrier follow-up, and document management. Its Insurance Virtual Assistant service also describes dedicated support for Personal Lines, Commercial Lines, Employee Benefits, and Life & Health workflows. Those published service areas make United Alliances a relevant provider for an agency that wants connected operational support across more than one stage.
An agency can bring a real account journey to United Alliances and ask for the proposed team's ownership map: what the assistant prepares, what a supervisor checks, what returns to the agency, and what evidence closes each stage. Confirm the assigned team's experience with the agency's AMS, carriers, and line of business. The result should be a specific operating scope rather than a blanket promise that every policy decision has been outsourced.
Make Each Stage Useful to the Next
The value of a lifecycle support model lies in the information that survives each transition. A quote should lead to a verified issued policy; a change should lead to an updated record or a visible exception; a renewal should begin with the account as it actually stands. Give the support team clear tasks and evidence rules, keep agency decisions with authorized people, and test the complete journey before expanding it.